

Role
Fixed assets
How do you know the equipment in the register still stands where it should? The register lives in a system, the assets in halls and offices, and between the two a year usually passes until the next count.
Intro call
Four questions we would start with
How do you know the register matches reality?
If it is from a count, it is worth remembering that for assets on a guarded site the law allows a count only once every few years - and most companies take that option. Between one and the next you work on a picture you know is drifting, you just do not know by how much.
Who notices first that an asset has changed location or user?
Usually nobody. Equipment wanders between departments, the person accountable changes, and the register shows the state of three years ago.
How long does your count take?
If it is several weeks with a dozen or so people, that is a cost that comes back every cycle - and much of it goes on retyping between a list and a spreadsheet.
What do you not do, even though you know you should?
Usually: writing off equipment that has long gone, and updating the places of use. Tasks that are never urgent, and through which the register drifts further from reality year by year.
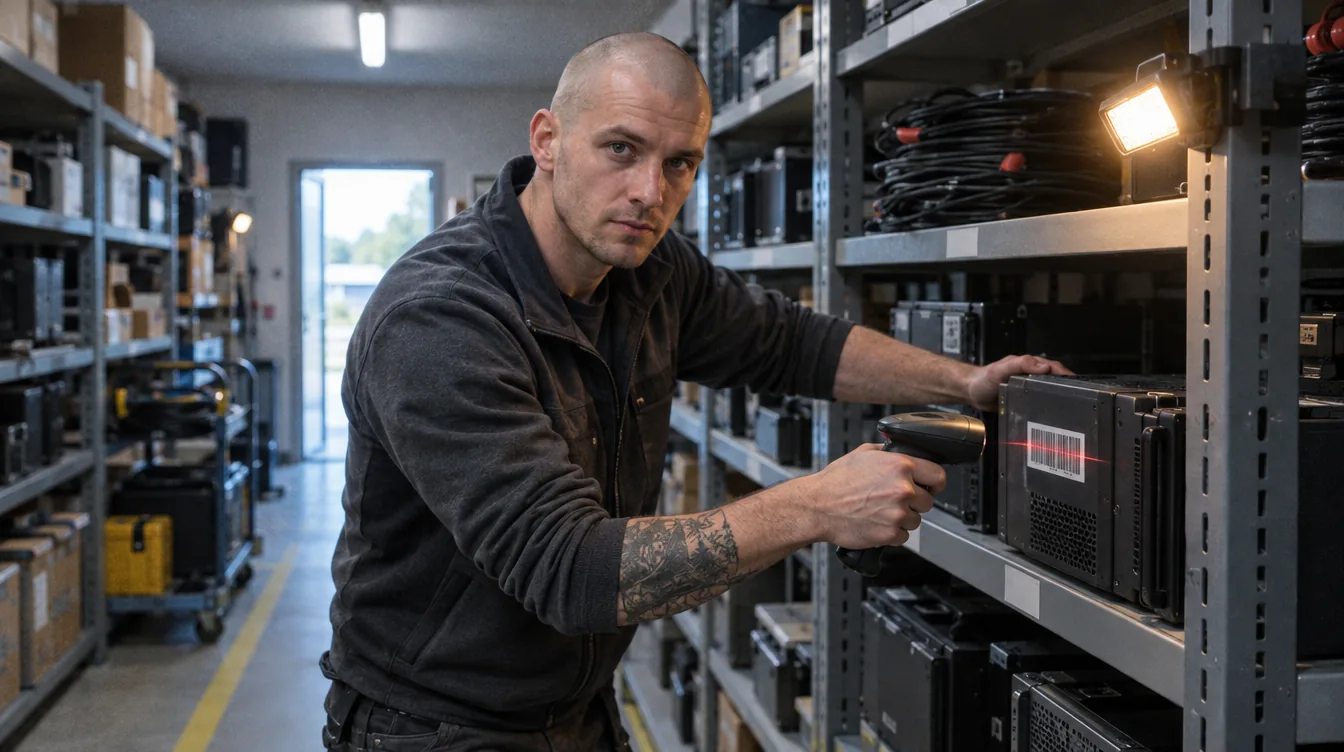
We take over the recording, you keep the decisions about the assets
Keeping the register, calculating depreciation, preparing and settling the count and checking it against the books can be taken off the desk. Decisions on write-offs, revaluation and classification stay with a person.
- A write-off always goes through a decision. - An asset missing from the count is information, not grounds for removal. What to do about it is settled by the committee or an authorised person.
- Classification and the rate are a decision, not a calculation. - The system proposes under your rules and flags the doubtful cases. The choice stays with the specialist.
- A discrepancy is dated. - It is known from when the register and reality diverge - and that is usually enough to establish what happened.
Scope
What can be taken off the asset register
Twenty example tasks. Each one has a human approval point. Below is a selection, and the scope we fit to your process.
Taking an asset onto the register
- Taking an asset on from the purchase and receipt documents
- A proposed classification and depreciation rate (decision: the specialist)
- Detecting purchases that should be fixed assets and went to expenses
- Assembling the initial value from every component
- Assigning a reference and linking it to a place and a person accountable
Depreciation and changes in value
- Calculating depreciation under the agreed rules
- Pointing out fully depreciated assets still in use
- Handling improvements and changes in value (classification: the specialist)
- Checking that accounting and tax depreciation agree
- Assets approaching the end of their depreciation period
The count
- Preparing count sheets broken down by location
- Recording the count without retyping into a spreadsheet
- The differences between the count and the register
- Pointing out assets not found and surpluses (decision: the committee)
- The report together with the settlement of differences
Write-offs and agreement with the books
- A register of write-off requests with the reasons (decision: an authorised person)
- Documentation of a sale or scrapping
- Reconciling the register with the ledger accounts
- Detecting assets with no place or person assigned
- Assets broken down by location for the insurer
A day's work
Today
- You enter new assets by hand from the purchase documents
- You settle the classification by looking for a similar asset in the register
- The count is paper sheets and a week of retyping
- You settle differences by phoning departments and reconstructing the history
- You learn equipment has been moved at the count
- Write-offs pile up, because nobody has time to file a request
With AI assistance
- An asset enters the register from the documents, you confirm the classification
- The doubtful cases are flagged before you sit down to them
- The count is recorded straight away, with no retyping stage
- You have the differences summarised, with the date of the last confirmed agreement
- An asset with no place or person assigned reports itself
- Write-off requests have a register and reminders
- The register against reality
the drift is caught during the year
a missing place or person is a signal, not an empty field
- How the count runs
the count ends in a settlement rather than in retyping
the result is recorded where the counting happens
- Correct depreciation
fewer retrospective corrections
the doubtful cases are flagged on receipt, not at the audit
- A record of write-off decisions
it is known who removed an asset and on what basis
the request and the decision are recorded together
We start with the next count, because it gives the reference point.
- Step 1
We put in order what is there
Assets with no place, no person, fully depreciated and still in use. The list is usually longer than the team assumes - and it shows the scale of the drift.
- Step 2
A count without retyping
The count recorded straight into the system, with the differences summarised. One cycle is enough to calculate the saving.
- Step 3
Receipts and depreciation
Entering assets from documents and calculating under the rules, with the classification approved.
- Step 4
Ongoing agreement
Signals about assets with no place or person, and a write-off register. This stage means the next count starts from fewer differences.
Common questions
Questions that come up at the first meeting
Will this role disappear if the register keeps itself?
The register does not keep itself - it drifts, and that is the whole difficulty of this role. We take over recording events and watching dates; what remains is judging whether spending is an improvement or a repair, and deciding the rates. Those are things a person answers for in front of an auditor, not a system.
Does this fall under the AI Act?
An asset register is not a high-risk use. The point to watch is assets assigned to people: that is employee data and it serves material accountability rather than assessing work - and it should stay that way.
Still have a question that is not here? Book a call

Next step
How many differences came out of your last count?
We will show you what an asset register looks like when the drift from reality is visible during the year and the count needs no retyping.